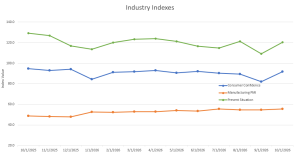
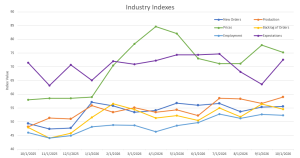
Economic activity in the manufacturing sector expanded in October for the 10th consecutive month, say the nation’s supply executives in the latest ISM® Manufacturing PMI® Report.
The Manufacturing PMI® registered 55.5 percent in October, 1 percentage point above the September figure of 54.5 percent. The overall economy expanded for the 24th month in a row. (Important data point reference: A Manufacturing PMI reading above 50 percent indicates that the manufacturing economy is generally expanding; below 50 percent indicates that it is generally declining. A Manufacturing PMI above 42.5 percent, over a period of time, indicates that the overall economy, or gross domestic product (GDP), is generally expanding; below 42.5 percent, it is generally declining. The distance from 50 percent or 42.5 percent is indicative of the extent of the expansion or decline.)
The Conference Board Consumer Confidence Index® rose by 7.5 points to 91.7 (1985=100) in October, up from 84.2 in September (a slight upward revision).
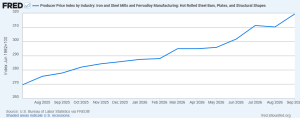
Please see the graphs for other notable indexes related to our industry.
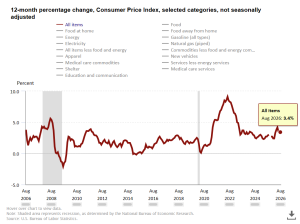
The Consumer Price Index (CPI, otherwise known as our “inflation” friend) wasn’t updated with October 2026 year-over-year data. Because of the 2025 lapse in appropriations due to last year’s government shutdown, we can’t report year-over-year comparisons this month. We do know that consumer prices rose 0.4% in October, more than expected, which complicated the Fed’s inflation fight.
CPI tracks the rate of change in US inflation over time, and the following shows the trends over the past 20 years.
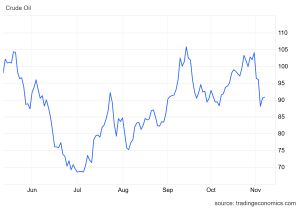
Crude oil rose to around $91 a barrel on Friday, erasing earlier losses as investors weighed the risk of renewed US-Iran military escalation against prospects for a diplomatic breakthrough. Investors are assessing whether the end of the US midterm elections could pave the way for renewed action against Iran, potentially threatening Middle East oil supplies. Iran reported attacks on oil tankers in the Strait of Hormuz on Thursday, while UKMTO data indicated vessel attacks were continuing at a near-record rate. Hopes for a diplomatic resolution emerged after Iran reportedly sent a nuclear proposal to Washington through Qatar. Significant obstacles remain over Iran’s nuclear program, with the US demanding that Iran give up its nuclear capabilities. Meanwhile, Iran demands the lifting of the US naval blockade, sanctions relief and the release of frozen assets before fully reopening the Strait of Hormuz. Crude plunged nearly 12% for the week.
The online US Oil Rig Count is currently reported as 604, which is up 6 compared to last month’s report and down 56 from November 06, 2025. This key and leading indicator shows the current demand for products used in drilling, completing, producing, and processing hydrocarbons, which we all use every day as fuel sources and finished products.
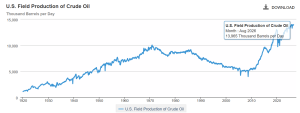
The number of rigs conducting oil and gas drilling in the United States remains stagnant, but efficiency has increased significantly over the years, as shown in the chart below. We continue to drill at record production levels. However, this trend of fewer rigs still reflects the priority of drillers to focus on efficiency and enhancing shareholder returns rather than expanding production through capital investments due to the previous administration’s desire to move away from fossil fuels. This philosophy might change now that the Trump administration is entirely behind fossil fuels. To provide context, in 2019, 954 rigs were drilling for oil and gas in the US, and, in 2014, there were 1609 rigs before oil prices dropped below $20 per barrel at the end of that year.
Tariffs have tightened, loosened, and will keep evolving as the Trump administration navigates global negotiations.
Whew… There’s still A LOT to unpack here, so hold on for the roller coaster ride.
A little background on where this all started and what it means. Tariffs are duties placed on foreign goods, paid by domestic importers to Customs and Border Protection at ports of entry. President Trump introduced tariffs on select Chinese goods in his first term in 2018, and President Joe Biden later maintained them, along with duties on steel and aluminum from most countries. In February 2025, Trump reinstated tariffs (10% higher on Chinese imports, bringing them to 35%, and 25% on Mexican and Canadian goods (except oil, taxed at 10%)). Since then, the environment has been ever-changing, with tariffs fluctuating month to month based on negotiations with other nations.
Tariff Update as of November 2026.
The tariff framework that has been taking shape all year is now largely set. Here is where things stand as of this month, with no major changes since last month’s newsletter, and what it means for you.
Section 122 Is Gone. Section 232 and 301 are the Laws of the Land.
As we reported last month, Section 122 expired by statute on July 24th, and Section 301 forced labor tariffs took effect at 12:01 am ET on July 24th.
Please refer to our prior newsletters for details on Sections 232 and 301. You can also find them on our website (click here).
Section 301 Is Being Challenged, and the Court Sounded Skeptical.
The challenge to the Section 301 forced labor tariffs, brought by small business importers and 25 states, was argued before the Court of International Trade on September 30th. The judges questioned both sides but appeared mostly skeptical of the government’s position. No ruling has been issued, and the court has not said when it will rule. The tariffs remain in effect until a court orders otherwise. Any relief could be limited to the named plaintiffs, as it was in the Section 122 case, and any ruling would likely be appealed. We will update you as soon as the court rules.
One More Section 301 Track to Watch.
The Office of the United States Trade Representative (USTR) is also investigating structural excess manufacturing capacity in 16 economies, including China, the EU, Japan, Korea, Mexico, and India, across 21 manufacturing sectors. A determination is due by March 11, 2027. Nothing has been decided. Any tariffs that come out of it would be a separate action from the forced labor tariffs.
China Update.
The U.S. and China trade truce, which was set to expire November 10th, has been extended to January 10th. Existing Section 301 tariffs on China remain in place and still stack with Section 232. If any portion of your supply chain has Chinese content, that exposure is real and worth understanding in detail.
One Process Change Worth Noting.
The petition-based inclusion process, which previously allowed domestic manufacturers and trade associations to formally request that specific HTS codes be added to the Section 232 scope, has ended. Going forward, Commerce and USTR will adjust product coverage on a rolling basis at their own discretion. There is no longer a formal submission window.
That rolling process is already at work. In August, the Commerce Department’s Bureau of Industry and Security (BIS) asked for public comments on adding 14 more derivative articles to Section 232, including parts of heat exchange units. Most would be taxed at 25% of full customs value. Comments closed August 27th. As of November 10th, we have not seen a final decision, and no effective date has been set. When BIS last added products, in August 2025, the change took effect within days, so there may be little warning. This would cover component parts imported separately, not the finished heat exchanger.
That means if you believe imported finished pressure vessels and heat exchangers should be explicitly covered under Section 232 derivative tariffs, engage directly with your elected officials. Not a petition. A phone call. A meeting. A letter.
As pressure vessel and heat exchanger fabricators, we need to keep pushing for protection for steel product manufacturers, not just domestic raw-material suppliers. We encourage every customer and partner in this industry to make that contact.
What This Means for Ward.
We continue to purchase 80 to 90 percent of our material domestically depending on the project. Our total material spend has increased approximately 15 to 30 percent since Section 232 tariffs were enacted, resulting in a 10 to 20 percent overall unit price increase after labor. We are absorbing what we can. We are passing through what we must. And we will continue to monitor the evolving situation and update you each month on the latest developments.
The administration has published several tariff fact sheets on the White House website (click here) as the tariff topic has evolved.
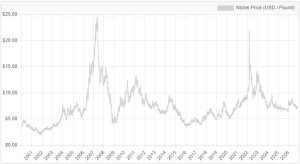
Nickel traded around $7.3709 per pound, extending its rebound to a two-week high as expectations of tighter Indonesian supply improved the market’s longer-term outlook. Indonesia, the world’s largest nickel producer, is considering more aggressive production quota cuts for 2027 through its annual RKAB approval system, following concerns that excessive output has contributed to a global surplus estimated at approximately 800,000 tons by Indonesian officials. The National Economic Council has also backed supply restrictions, while authorities indicated that future quotas would account for global market conditions and domestic smelter capacity. Additionally, potential production cuts by major producers, including Huayou and Tsingshan, could help moderate supply growth amid elevated exchange inventories. However, persistent oversupply, expanding nickel processing capacity, and slower-than-expected growth in battery demand continue to weigh on the market.
Plate mill plate lead times (weeks):
Domestic:
Stainless & Duplex: 12 to 13
Nickel Alloys: 12 to 18
Carbon steel: 13 to 32
*Keep in mind, some plates will exceed the estimated ranges depending on the mill’s production schedule and slab availability. *
Welded tubing lead times (weeks):
Domestic:
Carbon: 44+
Stainless: 14 to 16
Nickel Alloy: 14 to 22
Import:
Carbon: 22 to 30
Stainless: 16 to 30
Nickel Alloy: 16 to 42
Seamless tubing lead times (weeks):
Domestic:
Carbon: 10 to 16
Stainless: 8 to 14
Nickel Alloy: 8 to 14
*Lead times are accurate if bar is in stock. If not, lead times can increase to 44 weeks as most bars are of foreign melt. *
ASME head lead times (weeks):
Domestic:
Stainless: 7 to 22
Nickel Alloys: 7 to 22
Carbon steel: 7 to 25
*Keep in mind, some heads will fall outside the listed ranges depending on the alloy and size/thickness. Some head vendors stock common sizes (under 72” OD) and alloys, allowing them to ship next day. *
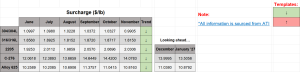
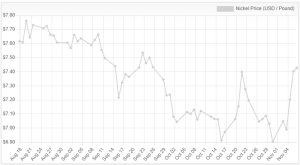
Nickel Prices have had an interesting ride over the past three decades, with a low of $2.20/lb. in October 2001 (following the September 11 events) and a high of $23.72/lb. in May 2007. Surcharges trail Nickel prices by about two months, so they would have been lowest in December 2001 (304 was $0.0182/lb.) and highest in July 2007 (304 was $2.2839/lb.).