
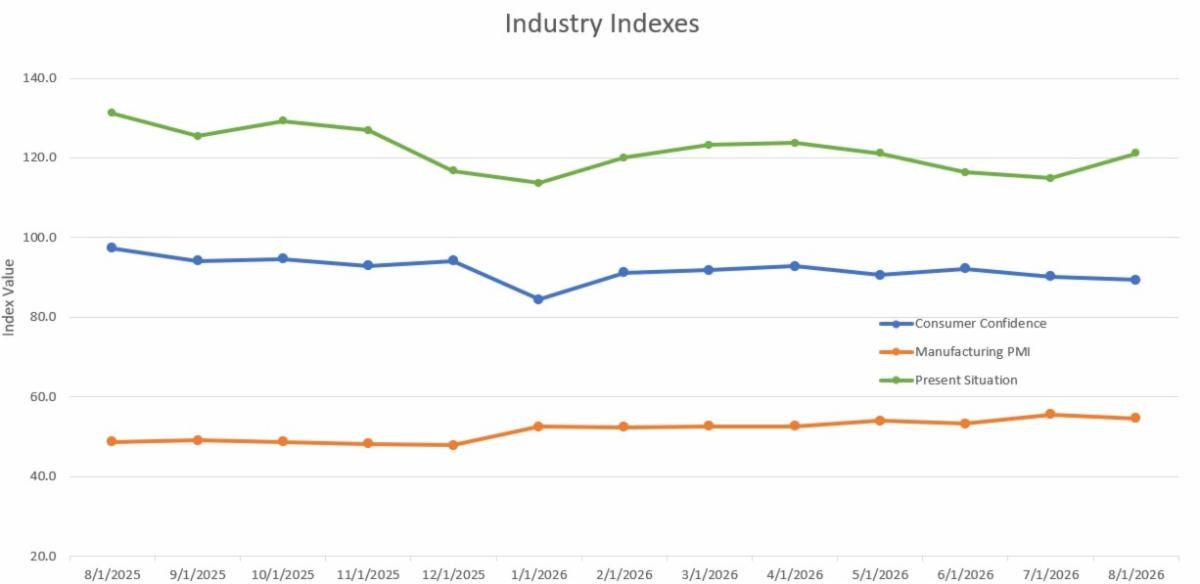
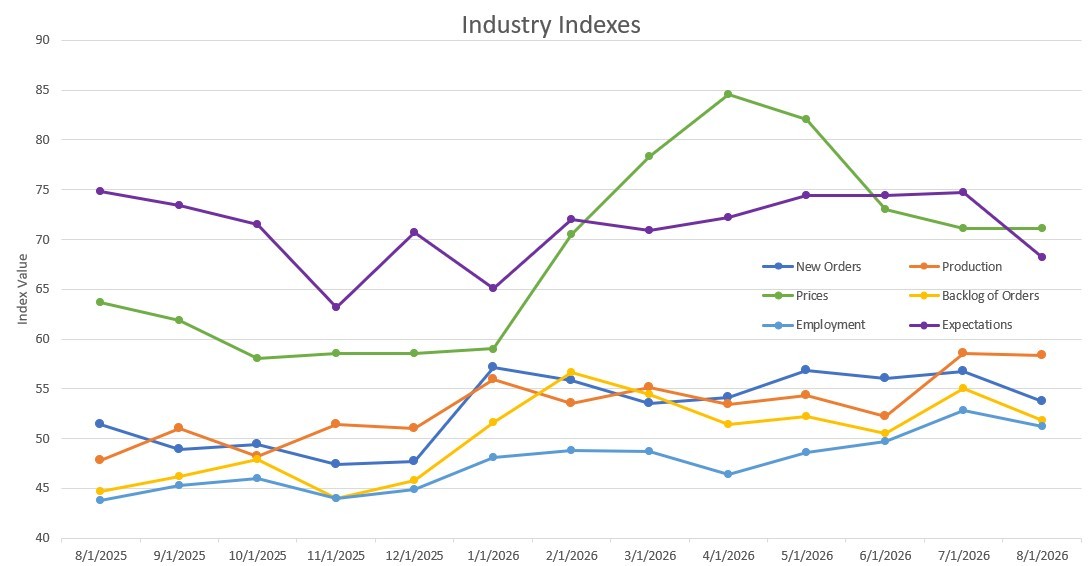
Manufacturing continues to expand, though most of the manufacturing and demand indexes we track ticked down in August. The ISM Manufacturing PMI eased to 54.6 percent from 55.6 in July, and the underlying subcomponents, new orders, production, and employment, all softened along with it, even as the headline reading stayed comfortably in expansion territory for the eighth straight month. Consumer confidence led that pullback, down 0.8 points to 89.4. CPI held roughly flat at 3.4 percent year over year, and material surcharges all trended up in September. The good news is alloy surcharges are trending back down heading into October and November, so we expect some relief there in the coming months.
Lead times are where we are seeing the most pressure right now, particularly on carbon steel plate and two-piece constructed heads at 10-foot diameter and greater. Data center demand is driving this. The data center market is the clear outlier in our industry right now, running at a pace we have not seen anywhere else. By comparison, the broader Petrochem market remains soft, while pharma and oil and gas are performing better than Petrochem but still not matching the data center pace.
Tariffs remain the story of the year, and the picture is largely set. Section 122 is gone. Section 232 and Section 301 are the law of the land.
Economic activity in the manufacturing sector expanded in August for the eighth consecutive month, say the nation’s supply executives in the latest ISM® Manufacturing PMI® Report.
The Manufacturing PMI® registered 54.6 percent in August, 1 percentage point below the July figure of 55.6 percent. The overall economy continued in expansion for the 22nd month in a row. (Important data point reference: A Manufacturing PMI reading above 50 percent indicates that the manufacturing economy is generally expanding; below 50 percent indicates that it is generally declining. A Manufacturing PMI above 42.5 percent, over a period of time, indicates that the overall economy, or gross domestic product (GDP), is generally expanding; below 42.5 percent, it is generally declining. The distance from 50 percent or 42.5 percent is indicative of the extent of the expansion or decline.)
The Conference Board Consumer Confidence Index® decreased by 0.8 points to 89.4 in August, down from an upwardly revised 90.2 in July.
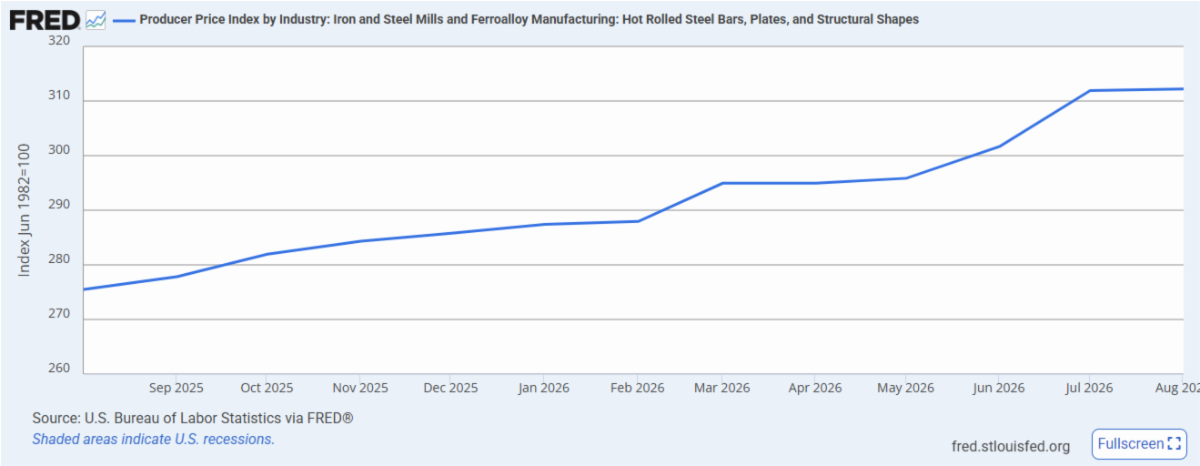
Please see the graphs for other notable indexes related to our industry.
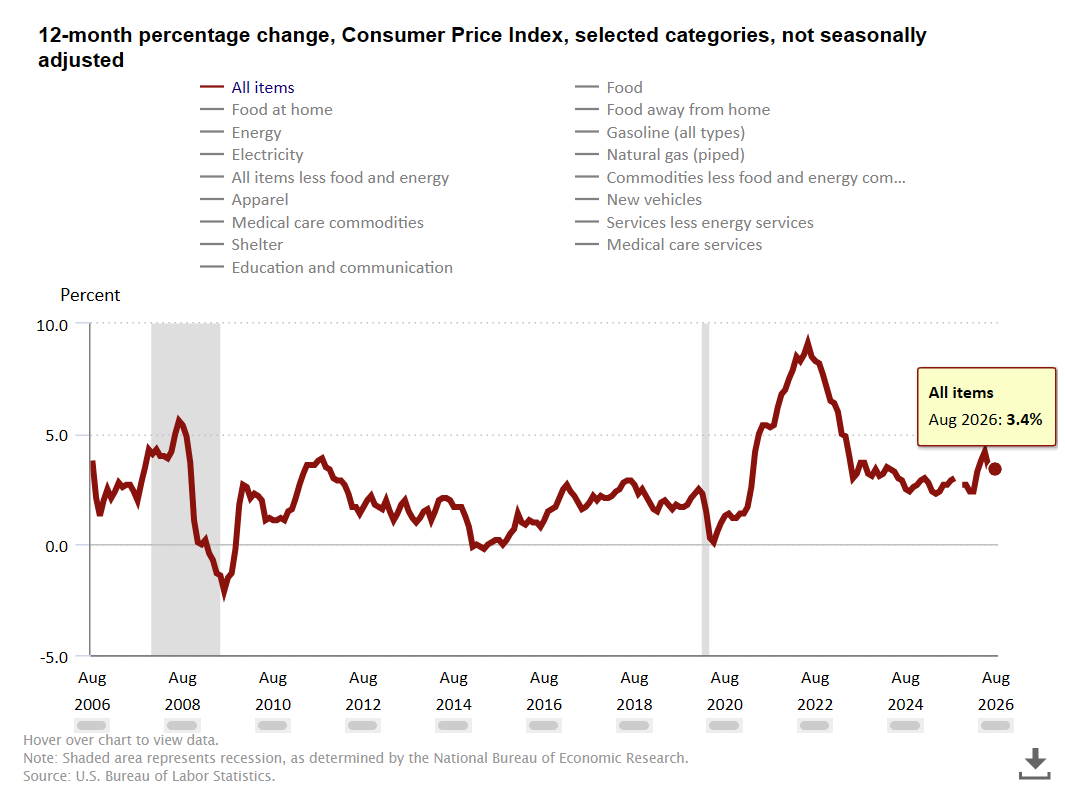
The Consumer Price Index (CPI, otherwise known as our “inflation” friend) is currently at 3.4% in August 2026, the same as in July 2026, and down from 3.5% in June 2026. CPI tracks the rate of change in US inflation over time, and the following shows the trends over the past 20 years.
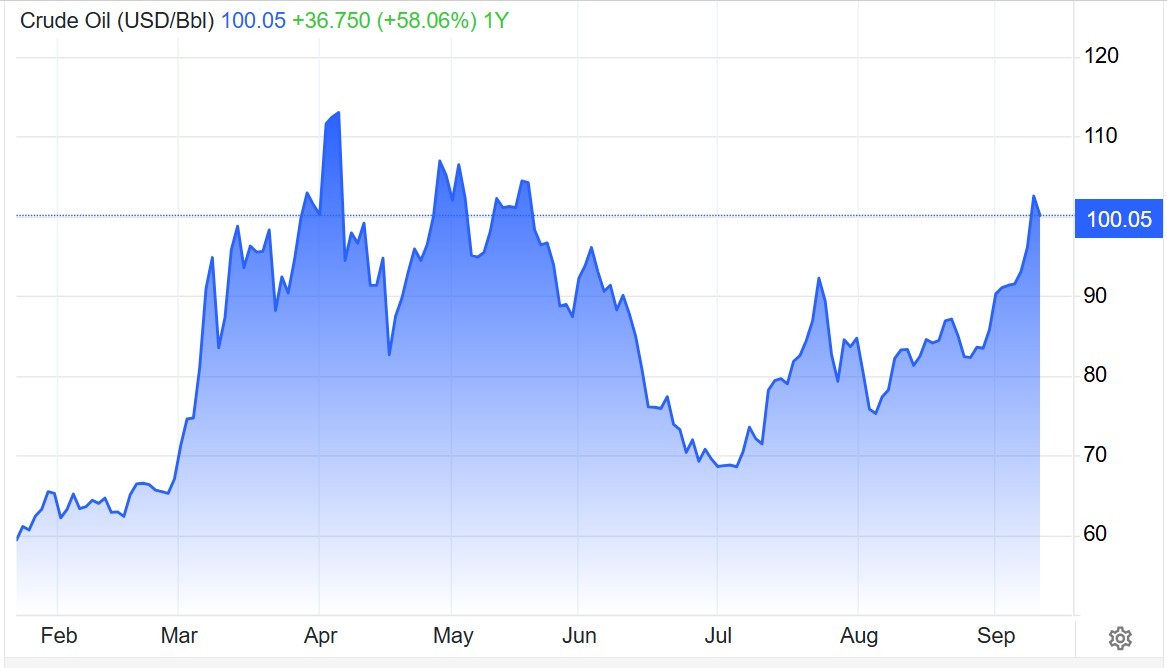
Crude Oil hovered around $100 a barrel on Friday. Iranian state media reported plans for talks with Gulf states in Oman. This suggests diplomacy is emerging even after a sharp escalation in tensions over the past week.
Top diplomats from the six member Gulf Cooperation Council are expected to meet their Iranian counterpart on Monday. They will discuss a possible temporary arrangement for managing shipping through the Strait of Hormuz.
Meanwhile the International Energy Agency sharply lowered its outlook for global oil demand. The IEA is forecasting a 2.5 million barrel a day contraction in 2026. That would be the largest annual decline since the Covid 19 pandemic. Higher prices and tighter supplies are weighing on consumption.
The IEA warned demand could weaken further if the conflict persists. OPEC cut its 2026 demand growth forecast for a fifth consecutive time. That is five months in a row of lower forecasts.
Despite Friday’s decline, oil rose for a second week. Houthi threats to Saudi Arabia continue to raise supply concerns.
The online US Oil Rig Count is currently reported as 591, which is up 3 compared to last month’s report and up 52 from September 12, 2025. This key and leading indicator shows the current demand for products used in drilling, completing, producing, and processing hydrocarbons, which we all use every day as fuel sources and finished products.
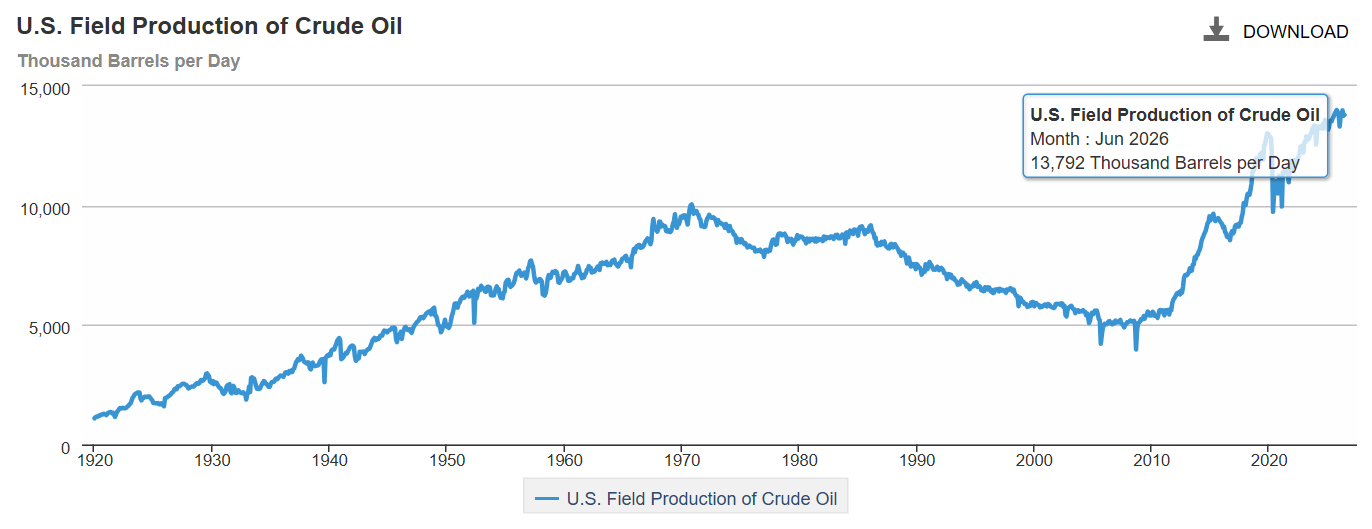
The number of rigs conducting oil and gas drilling in the United States remains stagnant, but efficiency has increased significantly over the years, as shown in the chart below. We continue to drill at record production levels. However, this trend of fewer rigs still reflects the priority of drillers to focus on efficiency and enhancing shareholder returns rather than expanding production through capital investments due to the previous administration’s desire to move away from fossil fuels. This philosophy might change now that the Trump administration is entirely behind fossil fuels. To provide context, in 2019, 954 rigs were drilling for oil and gas in the US, and, in 2014, there were 1609 rigs before oil prices dropped below $20 per barrel at the end of that year.
Tariffs have tightened, loosened, and will keep evolving as the Trump administration navigates global negotiations.
Whew… There’s still A LOT to unpack here, so hold on for the roller coaster ride.
A little background on where all of this started and what it means. Tariffs are duties placed on foreign goods, paid by domestic importers to Customs and Border Protection at ports of entry. President Trump introduced tariffs on select Chinese goods in his first term back in 2018, which President Joe Biden later maintained, along with duties on steel and aluminum from most countries. In February of 2025, Trump reinstated tariffs—10% more on Chinese imports, bringing them to 35%, and 25% on Mexican and Canadian goods (except for oil, taxed at 10%). From there, it has been an ever-changing environment, with tariffs fluctuating month-to-month based on negotiations with other nations.
Tariff Update as of September 2026.
The tariff framework that has been taking shape all year is now largely set. Here is where things stand as of September 2026 and what it means for you.
Section 122 Is Gone. Section 232 and 301 are the Laws of the Land.
As we reported last month, Section 122 expired July 24th by statute, and Section 301 forced labor tariffs took effect at exactly 12:01 am ET on July 24th.
Please refer to our prior newsletters for all the details outlined in Section 232 and 301 for your reference and use. You can also find them on our website (click here).
Section 301 Is Already Being Challenged.
On August 3rd, the attorneys general of 25 states, co-led by Oregon, Arizona, and California, filed a complaint in the Court of International Trade challenging the Section 301 forced labor tariffs as unlawful. Small business plaintiffs have filed separately as well. This is the same legal playbook that took down IEEPA and Section 122. We will be watching it closely. That said, Section 301 has survived more than 4,000 court challenges since 1974 and rests on far more durable legal authority than either of those. We do not expect this to move the needle in the near term, but we will keep you posted.
New Section 232 Aluminum Onshoring Incentive Program.
On July 20th, President Trump signed a proclamation establishing a new onshoring investment incentive program under Section 232. Companies that commit to build, refurbish, or expand U.S. primary aluminum production facilities and receive Commerce Department approval can import primary aluminum at half the otherwise applicable Section 232 tariff rate. Construction must begin no later than January 20, 2029. The proclamation does not extend the reduced rate to derivative articles or industrial equipment. This is a clear signal that the administration is serious about bringing primary aluminum production back to the United States.
One Process Change Worth Noting.
The petition-based inclusion process that previously allowed domestic manufacturers and trade associations to formally request that specific HTS codes be added to the Section 232 scope has ended. Going forward, Commerce and USTR will adjust product coverage on a rolling basis at their own discretion. There is no formal submission window anymore.
That means if you believe imported finished pressure vessels and heat exchangers should be explicitly covered under Section 232 derivative tariffs, the path forward is to engage directly with your elected officials. Not a petition. A phone call. A meeting. A letter.
As pressure vessel and heat exchanger fabricators, we need to keep pushing for protection for manufacturers of steel products, not just domestic suppliers of raw material. We encourage every customer and partner in this industry to make that contact.
What This Means for Ward.
We continue to purchase 80 to 90 percent of our material domestically depending on the project. Our total material spend has increased approximately 15 to 30 percent since Section 232 tariffs were enacted, resulting in a 10 to 20 percent overall unit price increase after labor. We are absorbing what we can. We are passing through what we must. And we will continue to monitor the evolving situation and update you each month on the latest developments.
The administration has published several tariff fact sheets on the White House website (click here) as the tariff topic has evolved.
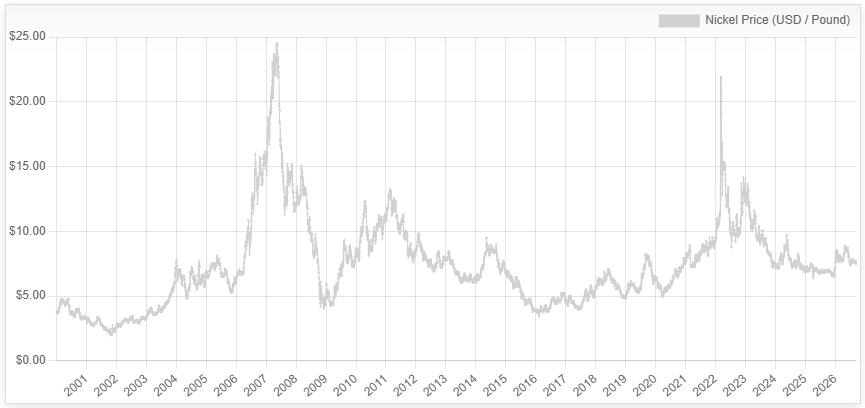
Nickel traded around $7.52 per pound in early September, its lowest level since July, as rising Philippine ore imports continued to offset Indonesia’s reduced 2026 RKAB mining quota. Indonesia cut its ore quota by roughly 30 percent, down to 260 to 270 million tonnes for 2026 from 379 million tonnes in 2025, yet LME warehouse stocks still rose in August to over 268,000 tonnes. Indonesia imported more than 11 million tonnes of Philippine ore between January and July, nearly double the volume from a year earlier, which replaced most of the withheld feedstock and kept smelters supplied. The cost of the quota policy is landing on Indonesian processors rather than on metal buyers, with rotary kiln electric furnace utilization falling to around three quarters, down from 84 percent a year earlier. Some reports suggest Indonesia may raise its 2026 quota later in the year, possibly to as much as 360 million tonnes, which would ease supply concerns further. Given elevated inventories and the market still not in a confirmed deficit, prices are likely to stay range bound in the near term.
Plate mill plate lead times (weeks):
Domestic:
Stainless & Duplex: 14 to 15 (previously 12 to 13)
Nickel Alloys: 13 to 14 (previously 7 to 12)
Carbon steel: 12 to 30 (previously 13 to 17)
*Keep in mind, some plates will exceed the estimated ranges depending on the mill’s production schedule and slab availability. *
Welded tubing lead times (weeks):
Domestic:
Carbon: 6 to 16 (no change)
Stainless: 8 to 18 (no change)
Nickel Alloy: 8 to 22 (previously 8 to 18)
Import:
Carbon: 14 to 25 (no change)
Stainless: 16 to 30 (no change)
Nickel Alloy: 16 to 42 (no change)
Seamless tubing lead times (weeks):
Domestic:
Carbon: 6 to 26 (no change)
Stainless: 8 to 26 (no change)
Nickel Alloy: 8 to 18 (no change)
*Lead times are accurate if bar is in stock. If not, lead times can increase to 44 weeks as most bars are of foreign melt. *
ASME head lead times (weeks):
Domestic:
Stainless: 6 to 16 (no change)
Nickel Alloys: 6 to 16 (no change)
Carbon steel: 9 to 16 (no change)
*Keep in mind, some heads will fall outside the listed ranges depending on the alloy and size/thickness. Some head vendors stock common sizes (under 72” OD) and alloys, allowing them to ship next day. *
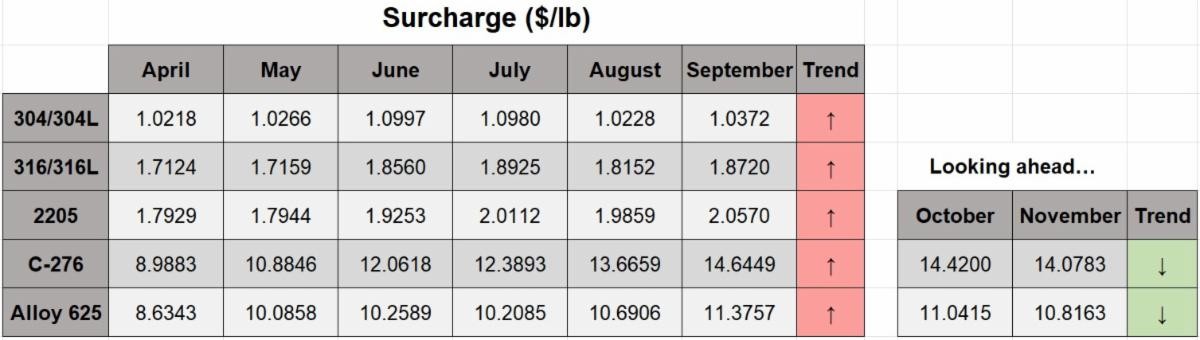
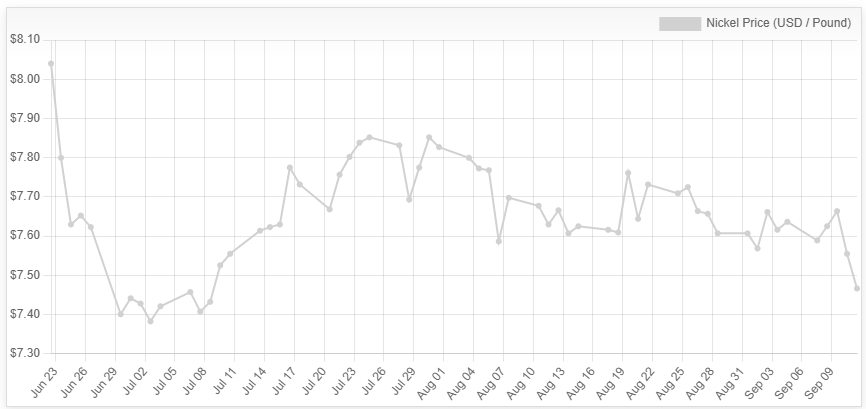
Nickel Prices have had an interesting ride over the past three decades, with a low of $2.20/lb. in October 2001 (following the September 11 events) and a high of $23.72/lb. in May 2007. Surcharges trail Nickel prices by approximately two months, so they would have been at their lowest in December 2001 (304 was $0.0182/lb.) and peak in July 2007 (304 was $2.2839/lb.).